German-French tax advisers · For companies · DE · FR · EN
Your business in Germany.Tax handled with clarity.
FRADECO is your German-French tax firm: we bring German accounting, tax, payroll and reporting together with what your international head office needs.
- 2 locations
- Bonn & Paris
- Expertise on both sides
- Rooted in Germany and in France
- DE · FR · EN
- Understood internationally
Interactive needs check
What do you need in Germany?
Pick your situation, mark the topics, send the enquiry — without leaving the page.
- 1Situation
- 2Topics
- 3Enquiry
Step 3 of 3
Where that puts you
Pick your situation and your topics above. The FRADECO services that fit will appear here — expandable, without leaving the page.
And now about you
Your selection travels with the enquiry — you do not have to repeat it.
Initial consultation
Thirty minutes
that sort a good deal out.
- Free initial consultation for companies
- 30 minutes
- We will send you the details for the video call by email before the appointment.
We offer companies a free initial consultation so that you get a first impression of us as a tax firm. You get to know the practice and describe your situation to us. Afterwards you receive a considered proposal on the costs to expect.
Please choose a time above.
Your appointment is confirmed.
Services
Master Germany.
Group-ready reporting.
We bring German tax and accounting expertise together with the processes of international groups.
01Day-to-day operationsGerman Accounting & Reporting
Bookkeeping to German requirements, annual accounts under the HGB and reporting packages for French or international head offices.
- Financial accounting
- SKR03 & SKR04
- HGB accounts
- Group reporting
- GDPdU & FEC
- ERP integration
- Running bookkeeping under SKR03 or SKR04 — in your system or in ours
- Monthly closes, account reconciliation and management of open items
- Annual accounts under the HGB including the notes and the filing with the Bundesanzeiger
- Reporting packages to group specifications — in your format and to your calendar
- Intercompany reconciliation with the parent company, so that consolidation does not stall on differences
- GoBD-compliant retention and the data extract from the German bookkeeping — as a GDPdU file for the Finanzamt, as an FEC file for the French parent company
ResultGerman figures that are right locally and can be used at head office without rework.
02Tax & filingsGerman Tax & Compliance
VAT, corporate and trade tax, the tax balance sheet and support through tax audits — deadlines and correspondence with the Finanzamt from one source.
- VAT
- E-invoicing
- Corporate tax
- Trade tax
- Tax audits
- Preliminary VAT returns, the annual return and the recapitulative statement
- Corporate and trade tax returns including the tax balance sheet and the reconciliation statement
- E-invoicing: receiving, issuing and retaining along the 2025 to 2028 deadlines
- Deadline monitoring, review of assessment notices and appeals where they are worth making
- Support through tax audits — preparation, data extract, correspondence
- Correspondence with the Finanzamt, handled entirely by us on request
ResultDeadlines, returns and dealings with the authorities from one source — and legible for international management.
03PeopleGerman Payroll & HR
German payroll and HR administration — from the first registration to looking after your staff month by month.
- Payroll
- Social security
- A1 & postings
- Wage tax
- HR services
- Monthly payroll including the wage tax return
- Registrations and deregistrations for social security, contribution statements and the U1 to U3 levies
- A1 certificates and postings — applied for before the first working day, not after it
- Certificates: employer, earnings and parental leave certificates
- Support through wage tax audits and the audit by the Deutsche Rentenversicherung
- Reports for HR and head office, in three languages on request
ResultA dependable German payroll with named contacts for HR and for your staff.
04Setting upSetup in Germany
A structured start in Germany: subsidiary, permanent establishment, tax registration and processes that hold from day one.
- Legal form
- Subsidiary
- Permanent establishment
- Registration
- Opening balance sheet
- The tax assessment: subsidiary, branch or permanent establishment
- Support through the notary appointment, the articles of association and the commercial register filing
- Tax registration with the Finanzamt, the VAT identification number and the employer number
- Opening balance sheet and set-up of the chart of accounts
- Building accounting and payroll processes from the first document
- An assessment of when a building or installation permanent establishment arises — before it does
ResultAn orderly start in which the structure, the registrations and the day-to-day processes fit together.
05AdviceAdvisory & Cross-border
Tax advice and structuring for your German business — from the running assessment to group structures, intercompany processes and transfer pricing.
- Transfer pricing
- Permanent establishments
- Treaties & withholding
- Intercompany
- Restructuring
- Transfer pricing: transaction matrix, documentation of the facts and of arm's length pricing, master file and local file
- Permanent establishments: building and installation cases, dependent agents and home office situations, profit attribution
- The Germany–France treaty, withholding taxes, relief procedures and exemption certificates
- Intercompany structures: service charges, financing, royalties and cost allocations
- Mergers, contributions in kind and the building up or winding down of German entities
- Tax audits with an international focus: strategy, correspondence, negotiation
ResultDecisions that hold up for tax purposes — and less friction between the German entity and head office.
06PresenceRegistered office
An official business address in Germany — usable in law, in trade and for tax, without an office of your own on the ground.
- Business address
- Commercial register
- Mail service
- Telephone service
- Meeting rooms
- An address that accepts formal service, for the commercial register, the Finanzamt, the legal notice and business partners
- Mail received, digitised promptly and forwarded at your rhythm
- Telephone service in German, French and English
- Meeting rooms for appointments with clients, banks or authorities
- Usable from the day the contract is signed — with no lease, deposit or service charges
ResultA permanent German address you can use from the day the contract is signed — with no lease, deposit or service charges.
FRADECO in Germany
Tax advice in Germany for international companies.
A French or international company starting to operate in Germany meets a tax, accounting and social security system of its own. FRADECO turns those requirements into clear routines for your German company, permanent establishment or taxable activity.
FRADECO GmbH works with companies only. We support the market entry into Germany, the tax registrations and the building of processes that hold. In day-to-day operations we take on financial accounting and the HGB accounts, preliminary VAT returns, corporate and trade tax, and German payroll and social security.
For head offices we bring local compliance together with reporting the group can use — from monthly closes and reporting packages to e-invoicing in Germany. Our teams in Bonn and Paris advise in German, French and English.
Topic hub Germany
Straight to the actual question — from the service to the answer.
Practical ways into the specialist questions people search for most — set out compactly and tied to the FRADECO service that fits.
Focus topic 2026
E-invoicing
& e-reporting
Germany and France are digitising the exchange of invoices along different routes. For international groups the real difficulty lies at the interfaces: formats, master data, processes, systems and filing routes all have to work together.
- ERP
- Accounting
- VAT
German expertise · international mindset
The German system.
Understood internationally.
Compliant in Germany. Usable across the group.
Our people in Bonn and Paris bring German tax knowledge together with an understanding of French and international group structures. German requirements become clear decisions, reports and processes for your head office.
- 01Specialists on both sides of the border
- 02Reporting that fits the logic of an international group
- 03Advice in German, French and English
FRADECO knowledge
German tax topics.
Current and explained.
German social security thresholds 2027: what the draft regulation means for employers
The draft regulation on German social security thresholds for 2027 has been published. The new ceilings, the special increase in health insurance and what employers should check before the turn of the year.
Electronic payroll records in Germany from 2027: What employers should prepare now
Germany’s exemption from keeping supporting payroll records electronically ends in 2026. Find out which documents are affected, how existing records are treated and what employers should prepare for 2027.
Company cars across borders: the employee’s residence decides the VAT
Where an employee lives in a different country from their employer, providing a company car can make VAT due at the employee’s place of residence. Since 1 July 2026 there is no concession.
E-invoicing in Germany: what has to be in place by 1 January 2027
From 2027, companies with more than 800,000 euros in prior-year turnover must issue e-invoices in Germany. The stages, the formats, and the cases that hold up the changeover in practice.
German VAT for foreign companies: what changes in 2027
Anyone storing goods in Germany or supplying private customers here becomes liable to German VAT — with no establishment in the country. From 2027, new registrations again mean two years of monthly returns.
Trade tax: a minimum multiplier of 280% from 2027
From 2027 a nationwide minimum multiplier of 280% applies to trade tax. What changes, who is affected and why an early review is worthwhile.
Input VAT on advance payment invoices: the BFH provides clarity
The Federal Fiscal Court has set out the requirements for deducting input VAT on advance payment invoices more precisely. What that means for investment projects and for invoice verification.
Guest article: market entry in the DACH region — the underestimated HR risks
Guest article by Axel Menzel (Inpact HR): posting, contractor or local employment, the employment contract as a steering instrument, co-determination — and why the exit belongs in the plan from the day you enter.
Tax-free crisis bonus 2026: the Bundesrat halts the EUR 1,000 relief
The planned crisis bonus of up to EUR 1,000, free of tax and social security contributions, has failed in the Bundesrat. What employers need to know now and why payments should wait for the time being.
Transfer pricing documentation: new duties and a 30-day deadline
A transaction matrix, a shorter deadline for producing documentation and duties to submit records unprompted: what the Fourth Bureaucracy Relief Act means for transfer pricing documentation.
EU Inc.: a new European company form — what businesses should know
With "EU Inc." the European Commission is proposing a new European company form: digital incorporation within 48 hours and uniform rules across the single market. What is planned and what stays national.
Artists’ social security levy 2026: annual return due by 31 March
Companies liable to the levy have to report by 31 March 2026 what they paid in 2025 to self-employed artists and journalists. Who is affected and what counts towards the assessment base.
E-invoicing 2026: the timetable to 2028 and what counts now
E-invoicing has been mandatory in German B2B since 2025. What EN 16931 actually requires, which transitional periods run to 2028, and why the XML file decides the input VAT deduction.
Invoice wording in English: the BMF allows other EU languages
Reverse charge, self-billing, margin scheme: mandatory VAT wording may now appear on German invoices in other official EU languages as well. What the BMF circular of 17 September 2025 means for international invoice layouts.
Verification of Payee: the IBAN name check in SEPA payments
Since October 2025 banks check on every SEPA transfer whether the payee's name matches the IBAN. What the traffic light principle means, where master data typically fails, and how companies avoid payment delays.
Minimum wage 2026 and 2027: what it means for mini-jobs and midi-jobs
From 1 January 2026 the minimum wage is EUR 13.90, and from 2027 EUR 14.60. That moves the mini-job threshold to EUR 603 and then EUR 633, and the whole transitional band with it. What employment contracts, payroll and budgeting need now.
Christmas bonus: entitlement, tax and social security
A Christmas bonus is voluntary — until established practice turns it into a legal entitlement. How special payments are treated under employment law, tax law and social security law.
The Christmas party: applying the EUR 110 limit correctly
Up to EUR 110 gross per participant, a staff event stays free of wage tax — as an allowance, and for no more than two events a year. For the input VAT deduction the same amount works as an all-or-nothing threshold.
Christmas gifts: the limits for employees and business partners
EUR 50 per business partner per year, EUR 50 per employee per month, EUR 60 for a personal occasion: which limits apply to benefits in kind, and why the documentation is what decides the outcome in a tax audit.
Artists’ social security levy falls to 4.9 per cent in 2026
From 1 January 2026 the levy rate for the artists' social insurance scheme falls from 5.0 to 4.9 per cent. What that means for companies commissioning artistic and journalistic work.
Special VAT audits: EUR 1.63 billion in additional assessments
Special VAT audits are faster and more targeted than a general tax audit — and they reach companies of every size. Which mistakes come up most often, and why foreign companies with a German registration are watched particularly closely.
Holiday pay in Germany: entitlement, tax and the recreation allowance
Holiday pay is not required by law in Germany, but it is fully subject to tax and social security contributions. How an entitlement arises through established practice, what applies during parental leave and sickness, and why the recreation allowance can be an alternative.
Transfer pricing adjustments and VAT: the open interface
Tax authorities increasingly link transfer pricing adjustments to VAT. What the CJEU cases Arcomet and Högkullen showed in 2025 — and why reliable guidance is still missing.
Immediate investment programme: declining-balance depreciation and a lower corporate tax rate
The Bundesrat gave its approval on 11 July 2025: 30% declining-balance depreciation, corporate income tax down to 10% in stages, a wider research allowance and higher limits for electric company cars. An overview with German-French structures in mind.
Confirming a VAT ID: digital only, through the BZSt
Since 20 July 2025 the Bundeszentralamt für Steuern accepts requests to confirm foreign VAT identification numbers by digital means only. Written and telephone requests no longer have any effect.
Cabinet adopts the immediate investment programme: 46 billion to 2029
On 4 June 2025 the federal cabinet adopted the immediate tax investment programme; the Bundestag followed on 26 June. What the package contains and where it takes effect for German-French companies.
Tax-free overtime: the plan in Germany, the model in France
The coalition agreement provides for tax-free overtime premiums. France has had the model for years — up to EUR 7,500 a year, with relief on social security contributions on top. A comparison for companies with staff in both countries.
HGB size classes: how companies in Germany are classified
Balance sheet total, turnover and headcount decide the size class under the HGB — and with it the accounting, audit and publication obligations. The thresholds at a glance, particularly relevant for French companies in Germany.
Workplace health promotion: EUR 600 per employee free of tax
Under § 3 Nr. 34 EStG, up to EUR 600 per employee per year stays free of tax and social security contributions — provided the measure is certified under the SGB V. Which programmes qualify, where VAT differs, and why a binding ruling is worth having.
The Growth Opportunities Act: the key changes at a glance
Electric company cars up to EUR 70,000, the gift threshold raised to EUR 50, declining-balance depreciation for a limited period, new rules for intra-group financing and mandatory e-invoicing from 2025 — relief worth EUR 3.2 billion.
WhatsApp at Work in Germany: When Messages Justify a Dismissal and When They Do Not
Deceit about an illness, defamation of a colleague, insults in a group chat: four German rulings show when WhatsApp messages can justify a dismissal and when an employer may not use them.
No article matches this selection yet.
Clients
Companies that
rely on us.
From the French group head office to the internationally run mid-sized business — looked after from Bonn and Paris.
In a short space of time Fradeco has become a knowledgeable and dependable partner. They respond to our particular wishes and concerns individually, react extremely quickly, and deal even with the most difficult matters promptly and entirely to our satisfaction.
The team is agile and knowledgeable, and it supports our growth by adapting continuously.
FRADECO
Two locations.
One team.
FRADECO supports French and international groups with every tax, accounting and administrative task in Germany — with specialists in Bonn and Paris, one settled multilingual team and short lines of communication.
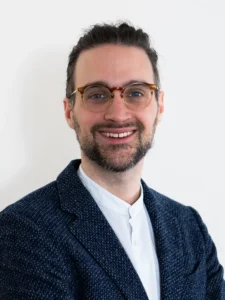
Michael StillerSteuerberater · Expert-Comptable
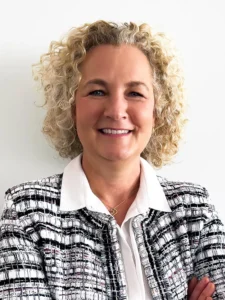
Susanne WienerSteuerberaterin · Wirtschaftsprüferin · Expert-Comptable
FAQ
Asked briefly.
Answered plainly.
Still have questions? A conversation usually settles where your case stands within minutes.
Which FRADECO website is the right one for my company?
For business and tax activities in Germany, FRADECO GmbH at fradeco.de is the one to speak to. For activities in France, fradeco.fr leads to FRADECO SAS. Both work in German, French and English.
Does FRADECO advise private individuals?
No. FRADECO works only with companies and groups that have business or tax activities in Germany.
Can you take on the entire payroll across borders?
Yes. We take on the complete payroll process, including the payslips, the filings with German or French bodies and the running correspondence with the authorities.
Do you advise in German and French?
Our multilingual team advises in German, French and English. Technical nuance is therefore lost neither in conversation nor in the documentation.
How does a change to FRADECO work?
After a structured first conversation we review the data, the deadlines and the processes already in place. We then coordinate the handover and set up a clear, secure way of working.
Do you support market entry into Germany?
Yes. We assess the subsidiary or permanent establishment for tax purposes, see the registrations through and build accounting, tax, reporting and payroll for the German operation in a structured way.
The next step
Put your business in
Germany on solid ground.
Tell us briefly about your German company, your site or what you are planning. We come back to you with a first professional assessment.
- FRADECO GmbH · Bonn
-
Simrockstr. 92 · 53619 Rheinbreitbach
+49 2224 123 14 83 - FRADECO SAS · Paris
-
50, Rue Chapon · 75003 Paris
+33 1 40 09 13 77